The perennial attractions of energy infrastructure investing include income, real asset exposure, and diversification. Energy infrastructure can provide diversification benefits in part because midstream MLPs and corporations are minimally represented in typical equity allocations, if at all. Additionally, MLPs and midstream tend to have moderate correlations with the broader equity market and other income investments. This note dives into the diversification benefits MLPs and midstream can provide portfolios.
Key takeaways:
- Standard equity allocations often have no MLP exposure and negligible midstream exposure, making duplicative positions less likely.
- MLP and midstream correlations with the S&P 500 are at multiyear lows of less than 0.3.
- MLPs and midstream can help diversify income portfolios. Current yields of 6.8% and 4.6%, respectively, are independent of interest rates.
MLPs/midstream unlikely to have notable overlap with existing equity investments.
Investors generally need to seek out meaningful MLP or midstream exposure as it is negligible or nonexistent in broad market allocations. This makes duplicative exposures in an equity portfolio less likely, which can be beneficial from a diversification standpoint.
There are only four midstream companies in the S&P 500 — Kinder Morgan (KMI), ONEOK (OKE), Targa Resources (TRGP), and Williams (WMB). Their combined weight in the benchmark is negligible, considering the entire energy sector is only 3.7% of the S&P 500 as of October 20. Even the Energy Select Sector SPDR ETF (XLE A) has limited exposure to midstream. The four names mentioned had a combined weight in the ETF of just 13.1% as of October 20, which is less than Chevron’s (CVX) weight alone.
MLPs can be particularly attractive from a diversification standpoint because they are excluded from broad market indexes altogether. MLPs are explicitly listed as ineligible organizational structures in the methodology for the S&P 500. In short, broad equity allocations are unlikely to have meaningful midstream exposure and probably have no MLP exposure.
MLP and midstream correlations with the S&P 500 are at multiyear lows.
Also notable from a diversification standpoint, MLPs and midstream have a very modest correlation with the S&P 500. As shown below, the rolling three-year weekly correlation with the S&P 500 is at a multiyear low at less than 0.3. Midstream MLPs are represented by the Alerian MLP Infrastructure Index (AMZI). Midstream is represented by the Alerian Midstream Energy Select Index (AMEI), which is 25% MLPs and 75% U.S. and Canadian corporations.
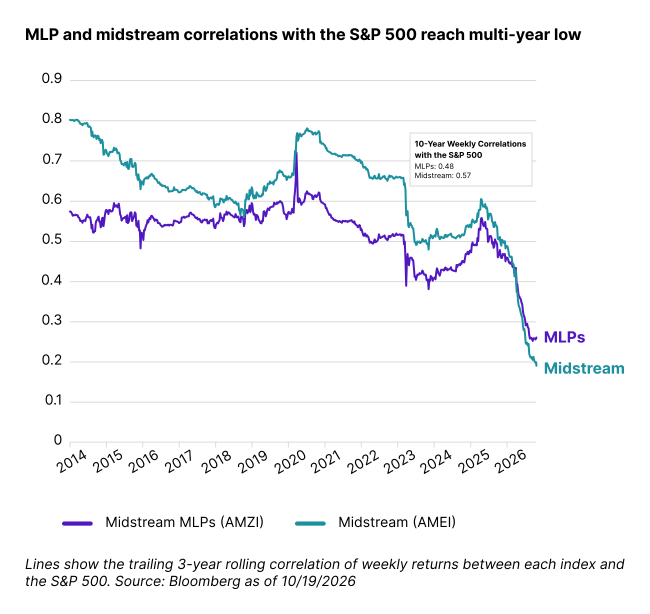
For most of the period shown, midstream (teal) had a higher correlation with the S&P 500 than MLPs (purple). The 10-year weekly correlation is also higher for midstream. More recently, however, MLPs have had a higher correlation with the broader market. For MLPs, the three-year correlation with the S&P 500 is 0.26, compared to just 0.19 for midstream.
MLPs and midstream can also diversify income portfolios.
MLPs and midstream have long been known for their income, with AMZI and AMEI yielding 6.8% and 4.6% as of October 20, respectively. Since investors are often allocating to this space in income portfolios, it is helpful to examine their diversification benefits relative to common yield-oriented investments.
As shown below, MLPs and midstream have moderate long-term correlations with REITs and utilities. MLPs have noticeably lower correlations with both compared to midstream. MLPs and midstream have no real correlation with the investment-grade bond benchmark. Of the indexes shown, MLPs and midstream have the greatest correlation with the high-yield bond benchmark.
| REITs (FNR5) | Utilities (S5UTIL) | Bonds (LBUSTRUU) | HY Bonds (LF98TRUU) | |
| MLPs (AMZI) | 0.38 | 0.33 | 0.02 | 0.51 |
| Midstream (AMEI) | 0.53 | 0.50 | 0.09 | 0.61 |
When discussing MLPs and midstream relative to bonds, it bears noting that bonds and equities have different risk profiles and yield drivers. Importantly, MLP and midstream yields do not fluctuate with interest rates, which can also be attractive for income investors. While bond yields have been rising, MLP and midstream yields are below their long-term average due to strong performance.
Over the last 10 years, the AMZI and AMEI have had average yields of 8.2% and 6.0%, respectively. Energy infrastructure companies continue to largely grow their dividends with no cuts to a regular dividend for an AMZI or AMEI constituent since July 2021.
Bottom line:
While investors often allocate to MLPs/midstream for income and real asset exposure, it is important to appreciate their diversification benefits as well.
Looking for midstream insights in your inbox? Subscribe here to keep a pulse on midstream investing through our weekly updates.
This article originally appeared on ETFDb.
AMZI is the underlying index for the Alerian MLP ETF (AMLP) and the ETRACS Alerian MLP Infrastructure Index ETN Series B (MLPB). AMEI is the underlying index for the Alerian Energy Infrastructure ETF (ENFR) and the Alerian Energy Infrastructure Portfolio (ALEFX).