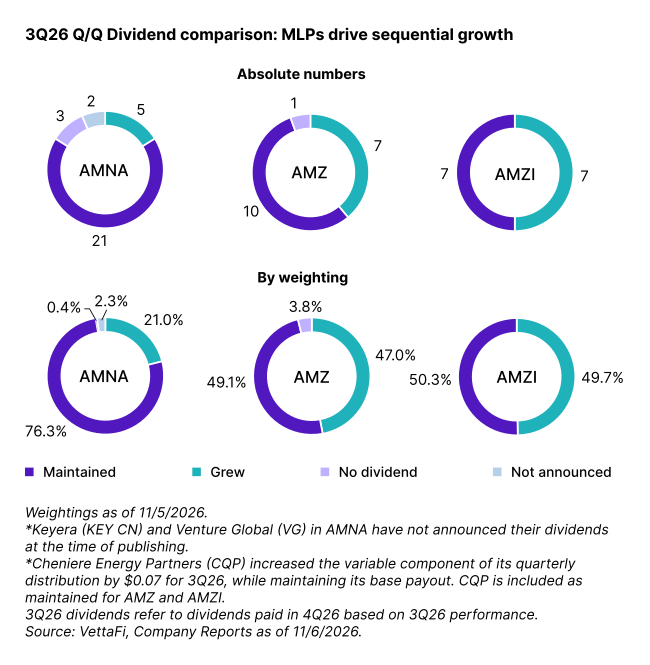
For the third quarter of 2026, sequential dividend growth across the broad Alerian Midstream Energy Index (AMNA) came primarily from MLPs. Midstream corporations mostly maintained their dividends, as they tend to prefer annual hikes with 4Q or 1Q payouts. The vast majority of midstream companies have increased their dividends on a year-over-year basis, and growth is expected to continue into 2027 and beyond. Learn more below about 3Q26 MLP/midstream dividends and 2027 guidance for payouts.
Key takeaways:
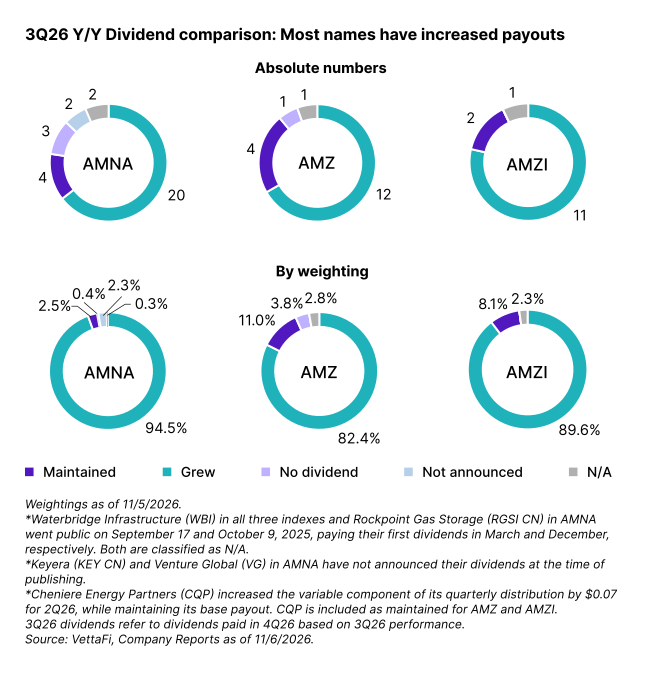
- On a year-over-year basis, 94.5% of the Alerian Midstream Energy Index (AMNA) by weighting has grown its dividends.
- MLPs largely drove sequential growth in payouts for 3Q26, while nearly all corporations kept their dividends steady. No AMNA constituent has cut its regular dividend since July 2021.
- Guidance for 2027 points to continued payout growth, with select companies planning double-digit percentage increases.
3Q26 payouts: Notable increases from MLPs and C-corps
Looking at sequential dividend increases, growth mainly came from the MLPs that typically grow their distributions each quarter. The majority of midstream names announce an increase once a year, and that often coincides with 4Q or 1Q announcements. Though many of the increases in 3Q26 were anticipated, growth was a mix of double-digit percentage increases and small hikes.
The largest sequential percentage increase and the standout dividend hike among C-Corps was from Cheniere Energy (LNG), which raised its dividend by 12.6% to $0.625 per share, representing a higher annual increase than last year’s 11% hike.
Among MLPs, MPLX (MPLX) increased its distribution by 12.5% to $1.2111 per unit, consistent with management’s commentary and the increase seen last year. Suburban Propane (SPH) announced a 7.7% increase to its distribution, the MLP’s first payout hike since 2021.
The remaining sequential increases came from names with a track record of growing their payout each quarter: Energy Transfer (ET), Sunoco (SUN), Hess Midstream (HESM), Global Partners (GLP), and Delek Logistics Partners (DKL). HESM and SUN are both on track to achieve their targets of at least 5% distribution growth in 2026.
The pie charts below show quarter-over-quarter changes to dividends for AMNA, the Alerian MLP Index (AMZ), and the Alerian MLP Infrastructure Index (AMZI) by comparing 3Q26 payouts to those made for 2Q26. To be clear, 3Q26 dividends refer to dividends paid in 4Q26 based on operational performance in 3Q26.
Year-over-year comparison highlights widespread dividend growth
With many companies only increasing their payouts once each year, a year-over-year comparison can provide a clearer picture of dividend trends. The pie charts below show a pronounced bias towards rising payouts. Over 80% of AMZ and almost 90% of AMZI by weighting have increased their distributions within the last year. For AMNA, 94.5% of the index by weighting has grown payouts relative to 3Q25. Looking at the absolute numbers, the majority of constituents in each index have grown their dividends.
Looking ahead to 4Q26 dividend announcements, more growth is anticipated. Midstream companies that traditionally raise their payouts once annually at the beginning of the year include Plains All American (PAA), ONEOK (OKE), Williams (WMB), Enbridge (ENB CN), TC Energy (TRP CN), and Gibson Energy (GEI CN). PAA’s framework calls for $0.15/unit annual distribution increases, which would mean ~9% growth on its current $1.67 annualized payout. Bellwether MLP Enterprise Products Partners (EPD) has been increasing its distribution twice a year, in January and July.
2027 dividend outlook remains broadly constructive despite some moderation
2027 dividend guidance was more measured for some names that have been growing their distributions at a healthy clip in recent years. MPLX noted on its 3Q26 earnings call that it expects a significant distribution increase in 2027, above its distributable cash flow growth. However, management cautioned that an asset divestiture could put the increase below its recent 12.5% pace.
HESM’s outlook was updated alongside a transaction with Chevron (CVX) announced in October. After one more increase for 4Q26, HESM expects to hold its quarterly distribution flat through 2027. It intends to maintain at least that level going forward, fully funded by adjusted free cash flow. That marks a shift from its prior target of at least 5% annual growth through 2028.
Elsewhere, guidance pointed to continued solid growth. C-Corp Targa Resources (TRGP) intends to recommend a 20% increase in its 2027 annual dividend to $6.00 per share. On its call, Cheniere reaffirmed its commitment to grow its dividend by at least 10% annually through the end of the decade. TC Energy (TRP CN) extended its annual EBITDA growth guidance of 5-7% to 2031, which accompanies plans to continue growing the dividend 3-5% annually.
SUN still targets multi-year distribution growth of at least 5%. It also returned to its leverage target less than a year after closing its Parkland acquisition.
Overall, company commentary and ongoing free cash flow generation continue to support a constructive outlook for midstream/MLP payouts. As of November 5, AMZ and AMZI were yielding 7.2% and 7.5% respectively, while AMNA was yielding 4.5%. Yields have moderated since the start of the year with strong performance, though they have risen since the summer as prices have come off their highs. AMZ, AMZI, and AMNA are up over 15% year to date through November 5 on a price-return basis.
Bottom line
Midstream/MLP dividend growth remains a reliable tailwind, reinforced by 3Q26 announcements. Consistent dividend growth supports compelling yields and provides attractive returns for investors. Complementing this payout growth are equity repurchases, which will be discussed in detail next week. Stay tuned.
For the latest insights on how energy infrastructure companies are capitalizing on North American LNG export growth, don’t miss our next virtual event, “How Midstream/MLPs Benefit from Booming LNG Exports,” on Tuesday, November 10, 2026, at 12:30 pm ET. Follow the link here to register.
This article was originally published on ETFDb.
vettafi.com is owned by VettaFi LLC (“VettaFi”). VettaFi is the index provider for AMJB, AMUB, MLPR, AMLP, and MLPB, for which it receives an index licensing fee. However, AMJB, AMUB, MLPR, AMLP, and MLPB are not issued, sponsored, endorsed or sold by VettaFi, and VettaFi has no obligation or liability in connection with the issuance, administration, marketing or trading of AMJB, AMUB, MLPR, AMLP, and MLPB.


